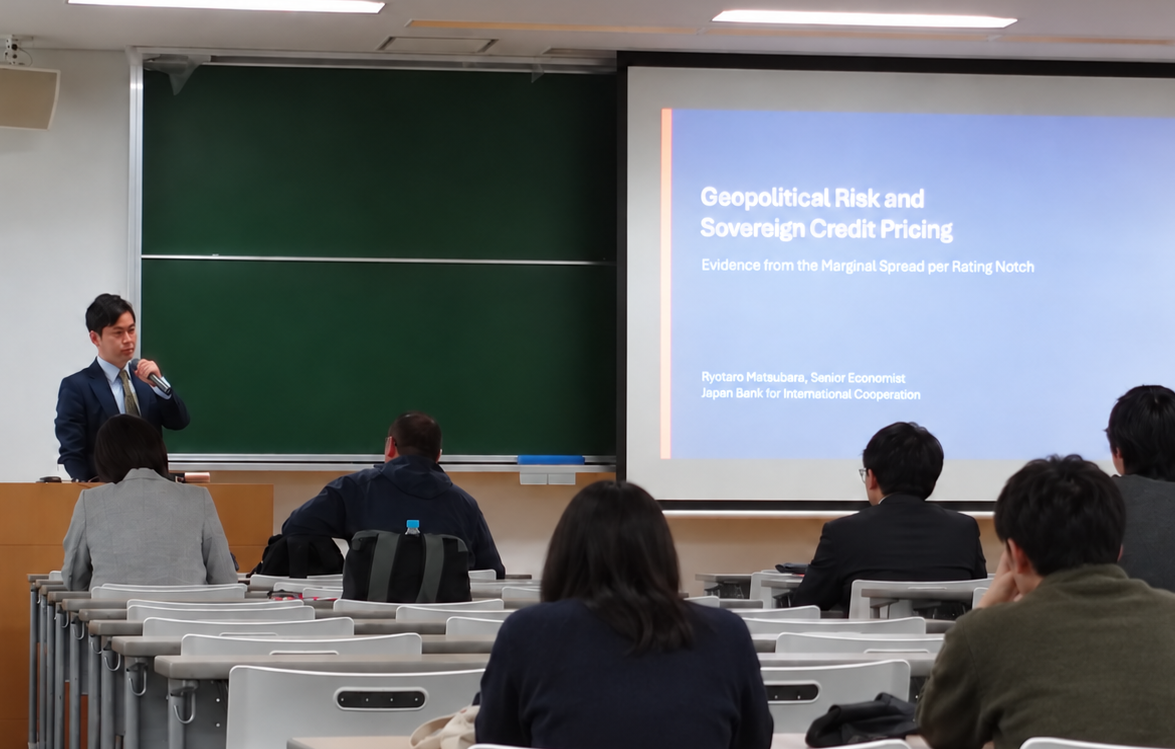


On October 3, 2026, Mr. MATSUBARA Ryotaro, Senior Economist at JBIC, presented a paper at the 85th Annual Meeting of the Japan Society of International Economics, held at Doshisha University, with Associate Professor DEMACHI Kazue of Tokyo University of Foreign Studies serving as the discussant.
Presentation Summary
In the presentation, he examined how geopolitical risk affects the pricing of sovereign creditworthiness in international bond markets. Specifically, the analysis focuses on the marginal spread per rating notch—the additional spread required by the market for a one-notch deterioration in a sovereign credit rating—and shows that, during periods of heightened geopolitical risk, lower-credit-quality sovereigns tend to face relatively more stringent market pricing. The analysis also distinguishes between realized geopolitical events, such as conflicts and military actions, and threats and tensions preceding such events, and finds a clearer relationship with the latter. These findings suggest that, particularly for lower-rated sovereigns that rely heavily on international bond markets, heightened geopolitical tensions may pose significant risks in terms of borrowing costs and market access.
JBIC is committed to contributing to the sound development of the Japanese and international economy and society by conducting research and analysis at the forefront of international finance, and by continuously accumulating knowledge on global economic and financial developments. Leveraging these insights, JBIC will continue to actively disseminate information through a broad range of channels.